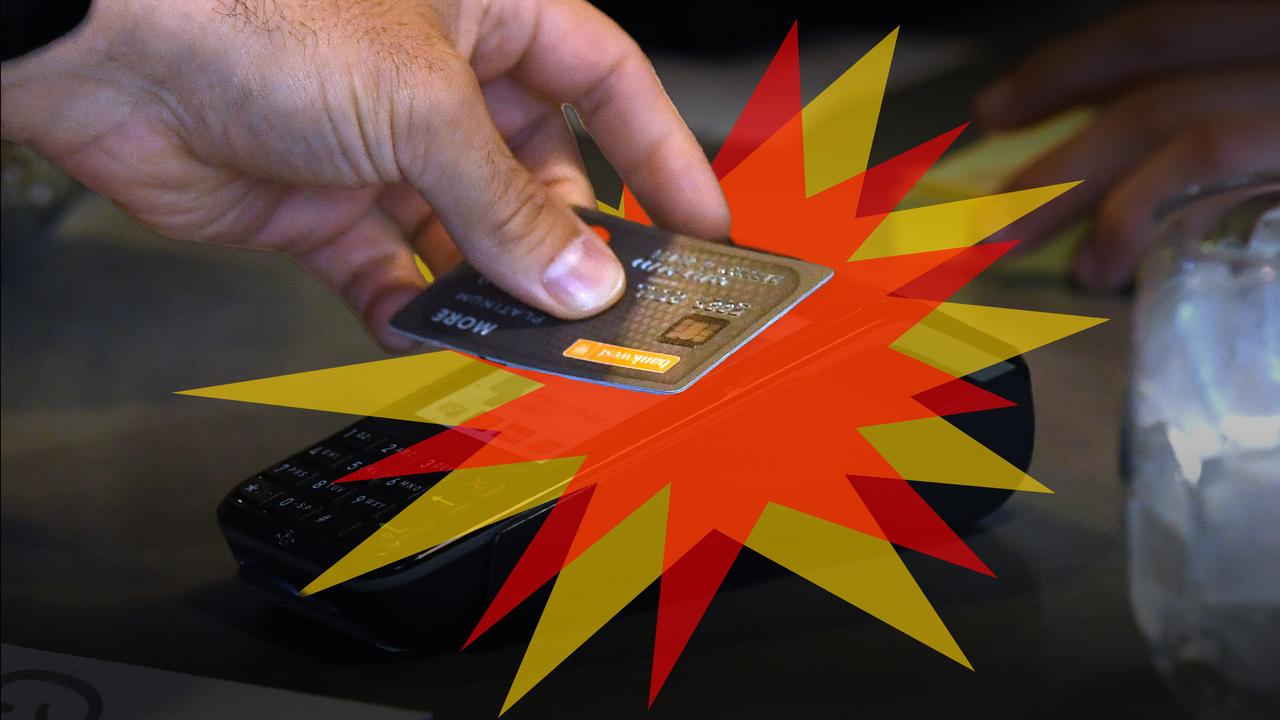
Australian businesses will need time to adjust to the new ban on card surcharges as the major banks prepare for a potential merchant fees war.
The change, driven by the central bank to give consumers transparency at the till, only came into effect on Thursday.
Commonwealth Bank of Australia says that from its end, the transition has been relatively smooth, although it has sensed pockets of anxiety.
“We do what we can at our end to support customers in making those changes,” head of retail sales and services Angus Sullivan told AAP.
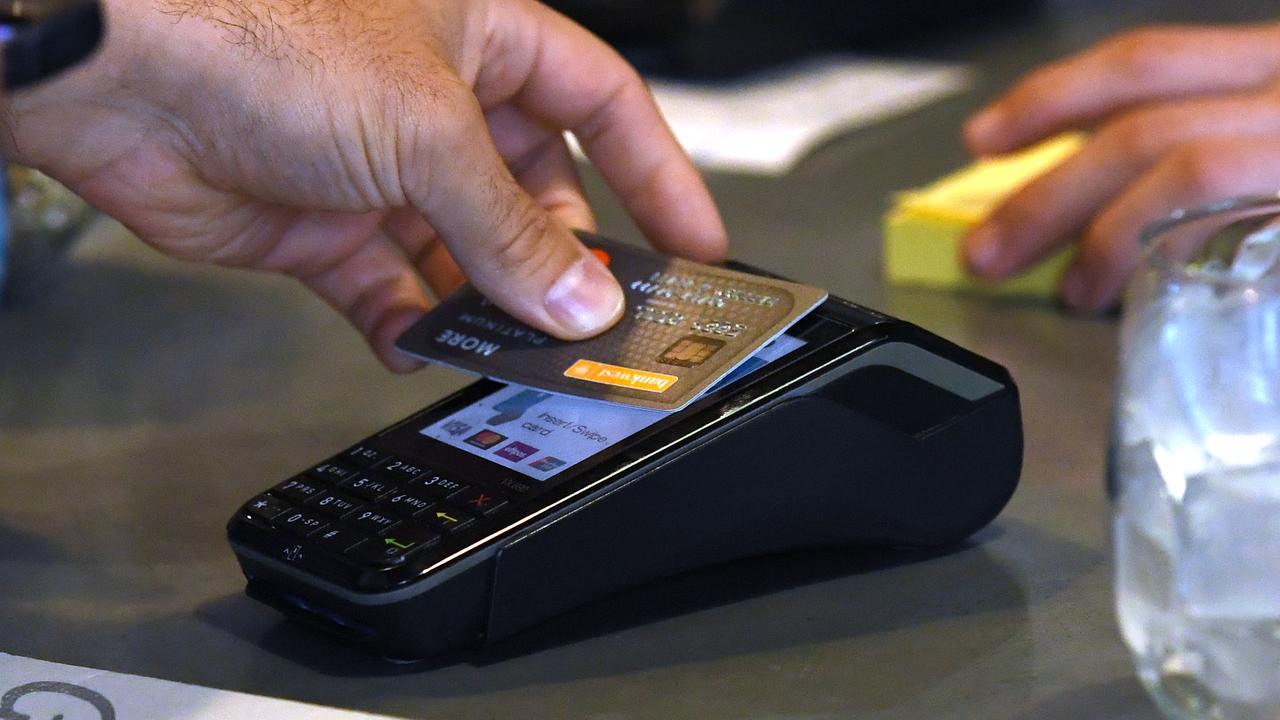
Even though consumers will no longer see the surcharge on eftpos, Visa, Mastercard and Amex transactions, businesses are still on the hook to cover the cost by either absorbing it or increasing product prices.
The banks have already remotely removed the surcharge option from the in-shop terminals used by merchants, including key hospitality operations that were the biggest fee users.
“That’s a big day of change, and I think there’s a lot to navigate as businesses work it out,” Mr Sullivan said.
At the same time, banks still have to cover the interchange fee – paid by the merchant’s bank to the customer’s bank when a payment is processed – even though it has now dropped to 0.3 per cent, from 0.8 per cent (roughly three cents on every $10) – and shopkeepers still pay merchant fees to their banks.
Commonwealth has just dropped its merchant pricing to 0.99 per cent, from 1.10 per cent, while last week Westpac cut its fee to 0.79 per cent, which it says is the lowest in the market.
“What it’s going to do is it’s probably going to create some more price-based competition for merchant services for businesses across the country,” Mr Sullivan said.
But Commonwealth, which has about 80,000 merchant payment terminals, is confident it can meet that competition, especially from the three main competitors: Westpac, National Australia Bank, and ANZ.
“Obviously, there are higher-priced merchant facilities that tend to bundle together a bunch of services,” Mr Sullivan said, in an apparent reference to flat-fee providers such as Square.
“But I think bundling will be more difficult in the future because businesses will want to understand: what am I paying for and do I actually need that?
“It’s a time of real change and a bit of confusion for a lot of businesses about how to navigate it and make sure they’re doing the right thing.
“We know how busy they are, how much they’ve got on.”
Meanwhile, bank customers are watching their institutions roll back lucrative credit card reward programs, hike annual card fees and limit previous benefits, because payment processing does not happen for nothing.
Asked if Commonwealth had seen any pushback from that, Mr Sullivan said that while the value proposition of a credit card was changing, his bank was “creating more ways for customers to earn points”.
This appears to be by encouraging clients to embed more of their business in the bank.
“We do see a lot of customers trying to navigate and work out what works for them,” he said.
Asked if the bank had noticed customers moving to lower-fee cards, Mr Sullivan said “not much”.
“We’ve seen a little bit of customers downgrading during the last month or two, but actually the attrition has been lower than we expected when we planned for these changes.”
Australian Associated Press is the beating heart of Australian news. AAP is Australia’s only independent national newswire and has been delivering accurate, reliable and fast news content to the media industry, government and corporate sector for 85 years. We keep Australia informed.