
The Australian stock market has fallen in line with Wall Street, where investors have whacked US technology companies after some earnings results fell short of expectations.
At noon on Monday, the main S&P/ASX200 index was down 28.3 points, or 0.32 per cent, to 8879.8, as the broader All Ordinaries shed 36 points, or 0.4 per cent, to 8989.4.
All the main US indices tumbled on Friday, with the tech-heavy Nasdaq suffering its largest one-day percentage drop since June 5 following disappointing quarterly results from Intel and Amazon.
The results have underscored growing worries about massive spending by companies on artificial intelligence and how soon those investments will begin to pay off.
Also weighing on Australian investor sentiment on Monday was the central bank, which is widely expected to raise interest rates again after its two-day monetary policy meeting ends on Tuesday.
“Investors are reluctant to take fresh risks ahead of Melbourne Cup Day, when the Reserve Bank of Australia is widely tipped to deliver its fifth interest rate increase of the cycle,” Moomoo Australia chief market strategist Tapas Strickland said.
Across the local market, consumer staples, materials and health sectors all lost more than one per cent, with the information technology subindex suffering the most after falling around two per cent led by drops in WiseTech, Technology One and Xero.
Among the big miners, BHP shed 0.8 per cent to $56.06, Rio Tinto lost 1.3 per cent to $145.34, but Fortescue was up 0.1 per cent to $14.28.
The banks were a bright spot, with Westpac up 1.82 per cent to $37.49 despite delivering a one per cent fall in annual profit to $6.8 billion.
National Australia Bank, which reports its annual results on Thursday, gained 0.7 per cent to $37.09, while Commonwealth rose 0.2 per cent to $166.36 and ANZ added 0.3 per cent to $40.93.
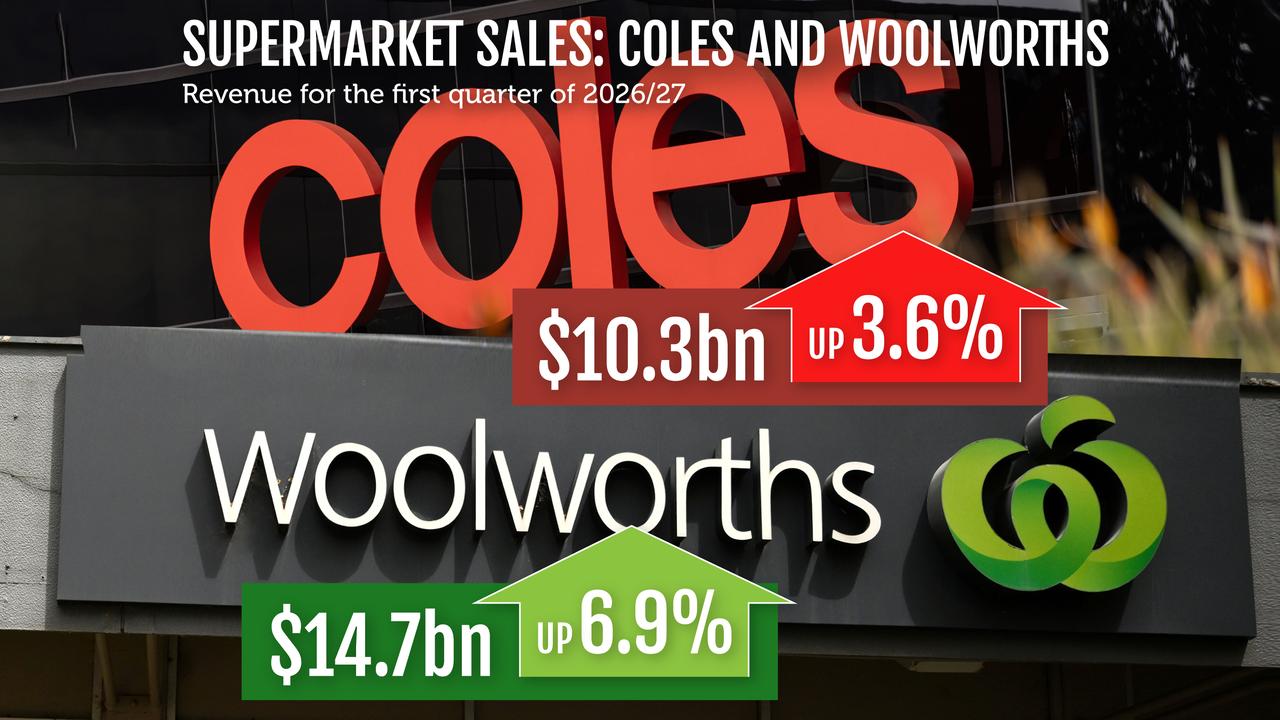
Elsewhere, supermarket giant Woolworths was 2.2 per cent lower to $39.33 and Coles also shed 2.2 per cent, to $21.16, amid ongoing concerns about how another rate rise will hit consumer spending.
Both companies released their first-quarter sales numbers last week and recorded increases that were broadly in line with expectations.
Qantas was also being sold, down 1.71 per cent to $8.64.
In company news, the owner of outdoor brands Kathmandu and Rip Curl revealed it has opened its data room to a potential buyer after booking a loss of $NZ416 million ($A334 million) for fiscal 2026.
KMD Brands had received a number of approaches but has for now settled on giving access to the US-based Bluestar Alliance, which owns the Scotch & Soda and Dickies brands.
Its shares rose 10.4 per cent to $1.65 even though the group cautioned that no transaction was guaranteed.
In the commodities market, Brent crude oil was trading around $US111.64 a barrel and spot gold was sitting at $US3920 ($A5,577) an ounce.
The Australian dollar was buying 70.31 US cents, down from 70.33 US cents on Friday at 5pm.
Australian Associated Press is the beating heart of Australian news. AAP is Australia’s only independent national newswire and has been delivering accurate, reliable and fast news content to the media industry, government and corporate sector for 85 years. We keep Australia informed.