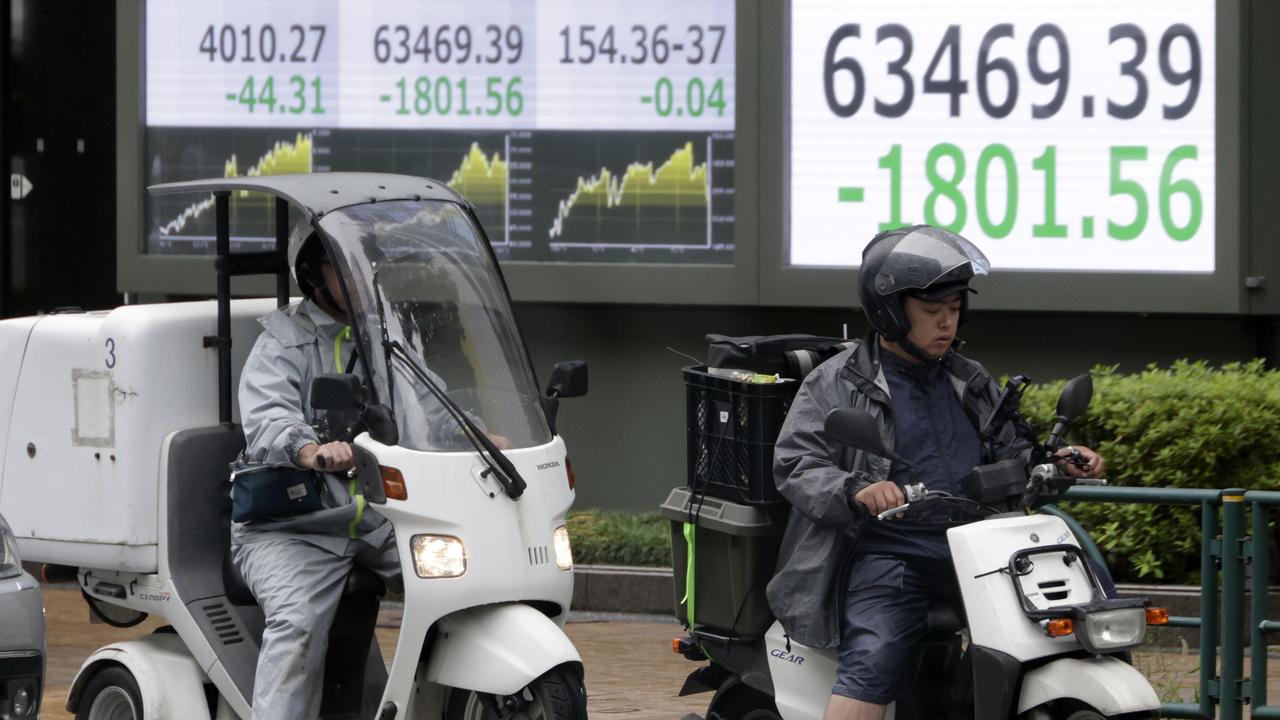
Asian shares fell on Friday as investors grappled with wild swings in bond and currency markets ahead of key US jobs data, while a widening military buildup in the Gulf kept oil prices elevated.
Bond markets were again the centre of volatility overnight, with the benchmark 10-year US Treasury yields hitting the highest since 2002 at 5.34 per cent after capping the biggest quarterly rise in 32 years. They later retreated and were steady at 5.2512 per cent in Asia.
Fiscal worries in France pushed the spread between French and German sovereign bond yields above 140 basis points, the widest since 2012, rattling European stocks and hitting the euro hard. The single currency slid as far as $US1.1215 ($A1.6185), the lowest since May 2025, and sank against the yen and the Swiss franc.
In Asia, MSCI’s broadest index of Asia-Pacific shares outside Japan fell 0.5 per cent and was on track for a weekly decline of 1.7 per cent. Japan’s Nikkei dropped 0.7 per cent but was set for a gain of 3.1 per cent for the week.
Mainland Chinese markets are closed for a public holiday through Wednesday of next week.
Nasdaq futures rose 0.3 per cent and S&P 500 futures inched up 0.1 per cent after the pullback in Treasury yields helped Wall Street stage a late rebound.
All eyes are on the US nonfarm payrolls due later in the day. Forecasts are centred on a rise of 90,000 jobs in September, while the employment rate is likely to be steady at 4.1 per cent. Much attention will be on hourly earnings after the ISM survey showed a huge jump in prices paid, pointing to more cost pressures.
“With the Fed now myopically focused on inflation and price pressures, a hot wages print could prove particularly influential for US rates, Treasuries and the USD,” said Chris Weston, head of research at Pepperstone.
“Risk assets have so far absorbed the rise in US real yields, and long-end nominal Treasury yields remarkably well. However, a sustained increase in term premium could be far more problematic.”
Markets currently price in a 25 per cent probability that the Fed will raise interest rates again in October, down sharply from 69 per cent a week ago after two top policymakers staked out an unusually clear case for taking in more data before deciding what to do next with interest rates.
However, a hike in December is still fully priced in.
Dovish comments from Fed officials drove a big rally in 2-year Treasuries overnight, with the yield curve bull steepening as short-end yields fell. The 2-year yield was last up one basis point (bp) at 4.8039 per cent, after falling 10 bps overnight.
The 10-year Treasury yield rose 2 bps to 5.2575 per cent, having dropped 6 bps overnight to ease from a 24-year high of 5.3445 per cent as the brutal sell-off finally tempted some buyers back into the market.
The rout in European bonds, with French yields hitting 14-year highs, may have also helped drive safe-haven flows back to US Treasuries, the dollar and the Swiss franc.
The US dollar index, which gauges the currency against six peers including the euro and franc, was firm at 102.09 on Friday, having rallied 0.6 per cent overnight to hit the highest level since April 2025. It is set for a third straight week of gains, up 1.1 per cent.
The euro was much weaker at $US1.1235 ($A1.6214), having slid 0.8 per cent overnight. It also sank against the yen and the franc , down 0.8 per cent and 1.0 per cent, respectively.
The yen traded at 158.13 per dollar after data showed underlying inflation in Japan’s capital accelerated to an annual rate of 2.7 per cent in September, bolstering the case for further interest rate hikes.
Oil prices remained firm on Friday after jumping overnight, with the US reportedly sending more troops and carriers to the Middle East. China also suspended oil product exports, stoking fears that global fuel shortages could worsen.
US West Texas Intermediate crude futures were steady at $US92.84 ($A133.99) a barrel, after finishing nearly 3.0 per cent higher overnight. The contract for Brent crude futures rolled, but they held above $US102 ($A147) a barrel.
Australian Associated Press is the beating heart of Australian news. AAP is Australia’s only independent national newswire and has been delivering accurate, reliable and fast news content to the media industry, government and corporate sector for 85 years. We keep Australia informed.