

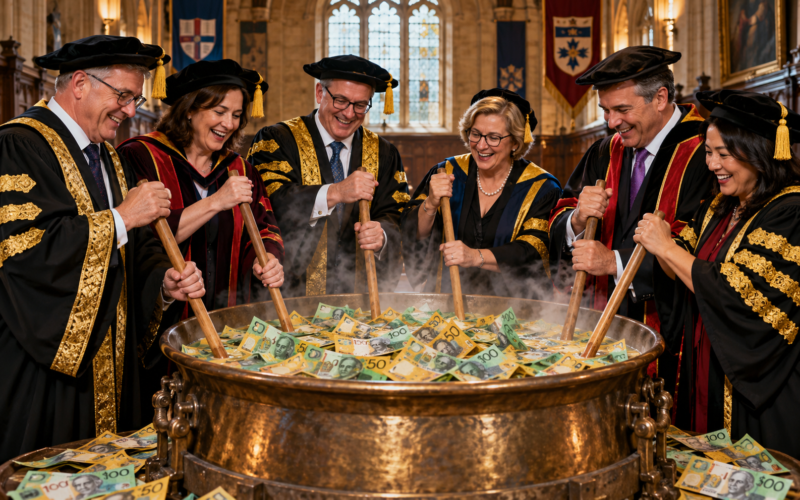

Universities are in crisis as spiralling costs and dwindling international student numbers force unis to cut costs. But it isn’t true, James Guthrie and Adam Lucas investigate.
Since 2019, across Australia, vice-chancellors and university media departments have been beating the same drum: public higher education is facing an existential financial crisis, leaving them with no choice but to slash courses, disestablish faculties, and make thousands of academics and professional staff redundant.
However, if you look at the audited statutory accounts lodged in various state and national parliaments, an entirely different reality emerges. Australia’s public universities hold billions of dollars in net assets, generate massive operating cash flows, and sit on substantial financial reserves.
How can a public institution be simultaneously broke and wealthy? The answer lies in an accounting trick and a fundamental misunderstanding of what financial numbers actually measure.
Rules of university accounting
Accounting is a system of identification, measurement, and disclosure. And any financial number only makes sense if you know the specific question being asked.
Consider a household budget. If you ask a family how much money they have, their answer depends on the framework they use. Their daily transaction account measures immediate cash and what they will spend week to week. Their dedicated savings account measures budgeted funds for future needs. Their total net worth includes their house, car, and superannuation funds. None of these figures is wrong: each answers a different question.
In Australian public university governance, four distinct accounting frameworks exist:
- Cash Accounting: Measures immediate liquidity, i.e. the cash coming in and going out to meet daily bills, utility expenses, and staff payroll.
- Fund Accounting: A public accounting method that measures whether public money has been spent strictly for the specific statutory purposes authorised by Parliament. For a public university, this means tracking whether public funding expenditure serves its legislated educational mission.
- Accrual Accounting: A business accounting method that measures overall long-term financial position and net worth, balancing physical assets against liabilities like borrowings and superannuation.
- Cost Accounting: A public accounting method that calculates the cost of delivering a public service, including direct and indirect teaching costs, building depreciation, and administrative overheads.
The problem is that university governance collapses when these four distinct measurements are conflated and incorporated into a single narrative that relies on just accounting numbers.
Unfortunately, many university leaders and their spokespeople now routinely engage in such conflations.
A manufactured crisis
In recent years, university executives supported by corporate advisory firms have routinely bypassed audited accrual statutory accounts in favour of non-statutory, managerial metrics known as “underlying operating results”.
This practice lets universities take a
‘choose your own adventure’ approach to accrual financial reporting.
Through a technique known as ringfencing, institutions selectively exclude profitable revenue streams such as investment returns, property dividends, or surpluses from offshore commercial subsidiaries while keeping all associated domestic operating expenses on their books.
As revealed in our investigation for MWM into Wollongong University Inc., this dual-ledger accounting transforms cash-wealthy institutions into manufactured victims of insolvency.
Wollongong University Inc. Profit over jobs as consultants prosper
The scale of this accounting sleight-of-hand across the sector is staggering. In 2024, the University of Sydney recorded a statutory operating surplus exceeding $545m, yet reported an “underlying loss” of $68.6m to its staff and the public. The University of Newcastle claimed a core operational crisis while its audited net assets grew from $1.3B to $1.8B.
At Macquarie University, management slashed 61 full-time teaching positions and 70,000 teaching hours under the banner of financial discipline, even as the consolidated entity held $4.3B in assets and generated $1.4B in annual revenue.
By presenting an artificially impoverished “underlying deficit” to staff, unions, and the public, vice-chancellors on their $1m+ salaries build the political cover needed to justify job cuts, course closures, the deletion of academic disciplines, and worse working conditions for tens of thousands of staff, all of which adversely
affect the livelihoods and quality of education for more than a million students.
Consultants and debt financing
If public university funds are not going into frontline teaching and research, where are they flowing?
The answer is found in the burgeoning “consultocracy” and speculative commercial property expansion. In our earlier investigations on consultants, slush funds, and secret ledgers, we exposed how major consulting firms Deloitte, KPMG, KordaMentha, McKinsey, and EY have become corporate mercenaries within higher education.
Universities routinely hire consultants at lucrative day rates to produce spreadsheets, ranking algorithms, and discipline viability models designed to justify job cuts. At the University of Wollongong, a KordaMentha partner was appointed interim Vice-Chancellor. At the same time, his firm prepared bids for restructuring work that eventually ballooned from $310,000 to $3.8m, a conflict of interest that sparked an Independent Commission Against Corruption (ICAC) inquiry, for which we await the findings.
University governance flaws exposed. End of consultants’ bonanza?
Over the last decade, public universities have taken on massive billion-dollar debt burdens to finance commercial property developments, private hospital ventures like MQ Health, and offshore subsidiary campuses through entities like UOW Global Enterprises (now “Global Education”) in the United Arab Emirates, India, Malaysia, Saudi Arabia and Hong Kong.
Student tuition fees and public funds intended for education are effectively cross-subsidising high-risk commercial real estate and offshore enterprises, while domestic academic capability is systematically hollowed out.
Wage theft and executive impunity
University staff and students have borne the full human cost of this corporate model. While academics face rolling redundancies and workload intensification, casual employees suffer from industrial-scale wage theft.
Stealing from workers has become an embedded feature of the corporate business model. When the Fair Work Ombudsman or courts penalise universities, such as the $32m remediation ordered at UNSW, the fines and legal fees are paid out of public institutional revenue pools, and no one has ever faced personal financial penalties or criminal prosecution for overseeing systematic underpayments.
Instead, the executive class continues to enjoy million-dollar compensation packages, performance bonuses, and extraordinary benefits such as Macquarie University providing its Vice-Chancellor with an $875,000 university-funded personal housing loan.
University wage theft. Australian academics owed hundreds of millions
Reclaiming the public mission
The final report of the NSW Parliamentary Inquiry into University Governance (Report No. 68) confirmed what our research has consistently demonstrated: contemporary university governance structures are fundamentally “not fit for purpose”.
To restore public trust, state and federal parliaments must enact structural legislative reform:
- Prohibit Non-Statutory Deficit Narratives: Ban universities from relying on underlying operating measures to justify restructures unless those figures reconcile fully with audited accrual statutory accounts.
- Mandate Itemised Transparency: Eliminate Treasury reporting exemptions so that every dollar spent on external consultants, capitalised asset advice, and executive benefits is fully disclosed in the annual report.
- Ringfence Public Funds for Public Education: Enforce strict fund accounting that prevents student fees and public grants from cross-subsidising commercial property ventures and offshore subsidiaries.
- Enforce Personal Executive Accountability: Hold Vice-Chancellors, university councils and senior executives personally liable for wage theft and administrative malfeasance, while restoring elected staff and student representatives to governing councils.
Universities are not private corporations, nor are they hedge funds with teaching arms.
They are statutory public trusts created by Parliament to advance scholarship, free inquiry, and public education. It is time to end the manufactured accounting crises and hold the university executive class accountable to the public interest and to being a public good.
Future Fund earns big returns on extortionate student accommodation

James Guthrie AM is Emeritus Professor in the Department of Accounting and Corporate Governance at Macquarie University. He is the joint founding editor of the Accounting, Auditing and Accountability Journal, which has been consistently ranked in the top five journals in his field.
Adam Lucas is an honorary senior fellow at the University of Wollongong and a founding member of Academics for Public Universities and Public Universities Australia. Prior to working at UOW, he was a researcher and policy analyst in the NSW Cabinet Office and the Departments of State and Regional Development, Aboriginal Affairs and Housing.