
European stocks have risen, extending a global equity rally as investors turned more optimistic before earnings season, while easing pressure in longer-dated bonds and lower oil prices helped calm markets after last week’s fixed-income turmoil.
The euro rose 0.2 per cent to 1.1239 on Tuesday morning after sliding to a 17-month low overnight, although concerns about the euro zone’s fiscal outlook persisted.
A sell-off in French bonds triggered by last week’s unpopular budget proposal showed signs of spreading across the euro zone at the start of this week.
Political uncertainty also increased after Spanish Prime Minister Pedro Sanchez called a snap election on Monday.
Bond markets stabilised on Tuesday.
France’s 10-year bond yield fell nine basis points to 4.77 per cent after surging to its highest since the 2000s last week.
Far-right leader Marine Le Pen, the frontrunner in the 2027 presidential election, said she wanted to cut France’s budget deficit to three per cent by 2030.
“European sovereigns have had a little bit of pressure coming off and France is looking in a better position overnight,” said James Klempster, deputy head of multi-asset at Liontrust in London.
“On the one hand you’ve got quite material pressure being felt on the government bond side. But elsewhere the corporate side of things actually don’t look too bad. You’ve got companies whose earnings remain very robust. We’re getting into the earnings season fairly soon, expectations for that are pretty high.”
The pan-European STOXX 600 rose one per cent, its third straight session of gains.
Nasdaq futures and S&P 500 futures added about 0.2 per cent after a technology-led rally lifted the Nasdaq to a record close on Monday.
Third-quarter earnings season begins next week.
Goldman Sachs estimates consensus forecasts imply 27 per cent growth in S&P 500 earnings, with more than half that coming from companies benefiting from AI infrastructure spending.
Nvidia, the world’s most valuable company and a bellwether for the AI trade, rose one per cent in premarket trading, putting it on track for a market value of about $US5.8 trillion ($A8.3 trillion).
Brent crude fell 0.4 per cent to $US99.91 a barrel after dropping 1.9 per cent overnight as resilient Middle East crude exports and a G7 emergency stockpile release eased supply concerns, though ongoing security risks in the region limited losses.
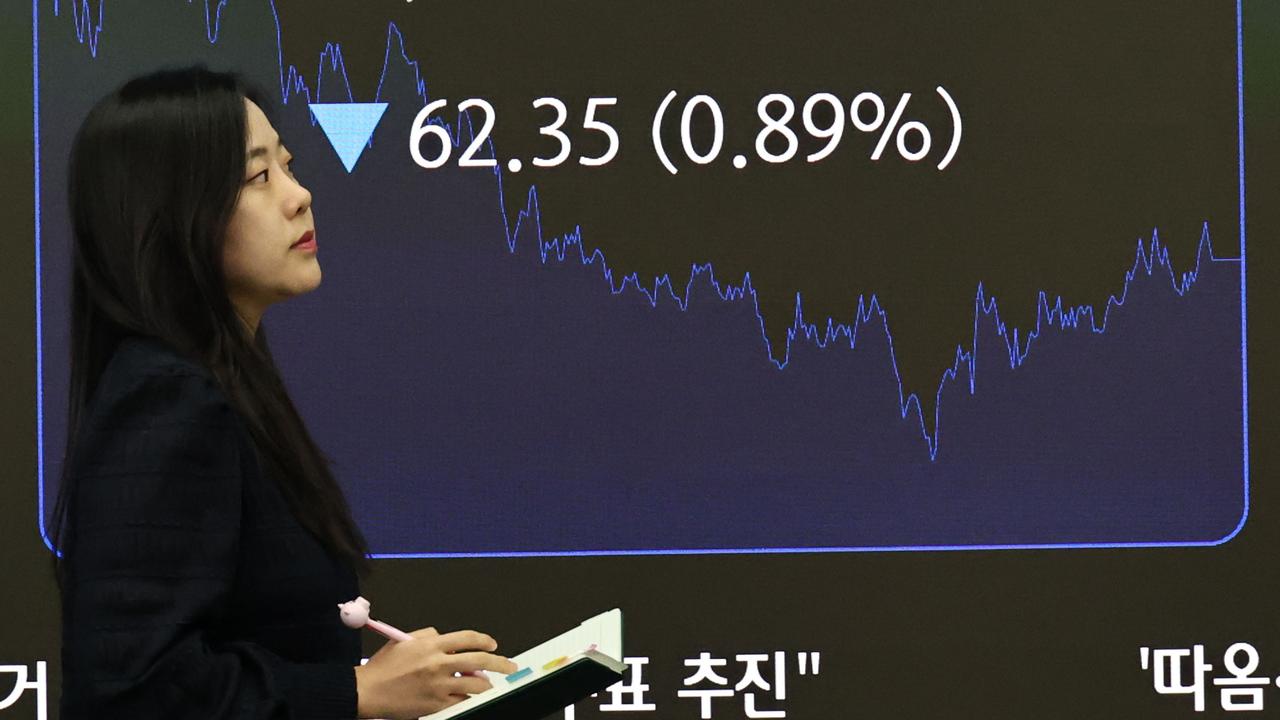
Most Asian markets rose. Japan’s Nikkei gained 1.1 per cent and Hong Kong’s Hang Seng index added 0.7 per cent, while South Korean shares fell nearly one per cent after reopening following a holiday.
Although the bond sell-off showed signs of easing, sovereign yields remained near multi-year highs as investors grappled with persistent inflation and debt concerns.
The premium investors demand to hold French 10-year bonds over safer German debt narrowed to 129.79 bps after widening last week to its highest level since the euro zone debt crisis in 2011.
German 10-year bond yields, the euro zone benchmark, dropped 5 bps to 3.44 per cent.
Long-dated US Treasury yields also eased after touching fresh 24-year highs overnight.
The 10-year yield fell 3 bps to 5.2815 per cent, while the 30-year yield dropped 2.8 bps to 5.6356 per cent.
Yields have risen sharply even as markets scaled back expectations of a Federal Reserve rate increase following a soft US jobs report and policymakers’ calls for more evidence before further tightening.
The dollar weakened broadly against most major currencies.
The dollar index fell 0.16 per cent to 101.99 after rising 3.5 per cent during the past month.
Spot gold rose 0.3 per cent to $US4,152.97 an ounce.
Australian Associated Press is the beating heart of Australian news. AAP is Australia’s only independent national newswire and has been delivering accurate, reliable and fast news content to the media industry, government and corporate sector for 85 years. We keep Australia informed.